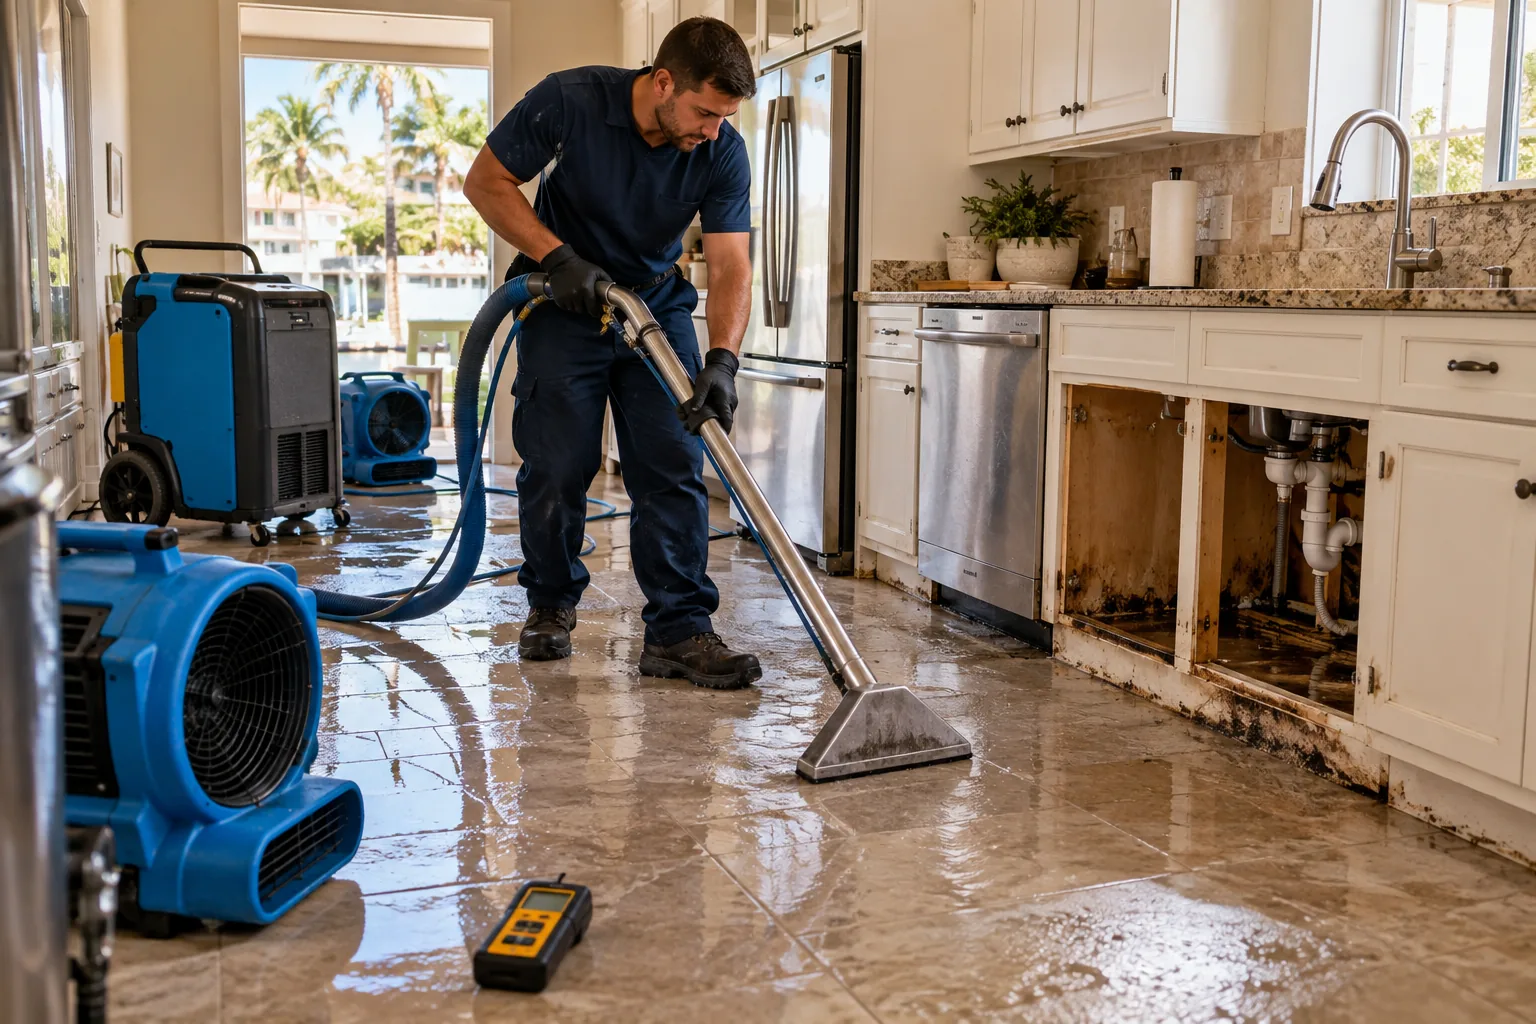
Florida Condo & HOA Property Damage Restoration Guide
Water from the unit above. A hurricane-damaged roof nobody ‘owns.’ SB 4-D milestone inspections reshaping every budget. Condo restoration in Florida runs on different rules — here they are, plainly explained.
Coverage entries describe the service-area directory and do not represent a physical office at every listed ZIP.
Who Pays: Unit Owner, Neighbor, or Association?
The first question in every condo loss — and the one that causes most disputes. The general framework under Florida’s condominium statute (Chapter 718):
Damage inside your unit, from your unit
Your HO-6 (condo unit owner) policy is primary — burst supply line in your bathroom, appliance leak, kitchen fire. Your deductible, your claim, your contractor coordination (with association notification).
Damage from a neighboring unit
The classic: upstairs neighbor’s water heater floods your ceiling. The neighbor’s HO-6 typically responds for their liability; your HO-6 covers your repairs. Document everything — inter-unit disputes live and die on documentation of source and timeline.
Common elements (roof, exterior, hallways)
The association’s master policy covers common elements — roof, building exterior, shared plumbing stacks, lobbies. Unit owners generally can’t (and shouldn’t) hire their own roofer for association property.
Limited common elements (balconies, etc.)
The gray zone. Responsibility splits vary by declaration — read your governing documents. Balcony-origin water intrusion is one of Florida’s most litigated condo issues precisely because documents differ.
The declaration controls
Your association’s declaration of condominium defines unit boundaries and maintenance responsibilities — and it overrides general rules. Before any dispute, read it. Before any work on common elements, notify the association in writing.
SB 4-D Milestone Inspections: What Owners Must Know
After the Surfside tragedy, Florida’s SB 4-D (and related legislation) imposed milestone inspections for aging condominiums — generally buildings 30+ years old (25+ within 3 miles of the coast) — plus structural integrity reserve studies and mandatory reserve funding. What this means for restoration:
Inspections find damage that becomes restoration work. Milestone inspections routinely uncover concrete spalling, rebar corrosion, waterproofing failures, and water intrusion — each converting into a restoration/remediation project with association-level budgets. Reserve funding changes the money conversation. Associations now fund reserves for structural components, which affects how special assessments and restoration projects are financed — ask your board how current projects align with the reserve study. Timing matters. Inspection-driven repairs have statutory deadlines; delaying turns a planned project into an emergency one at emergency prices.
HO-6 vs. Master Policy: The Two-Layer System
Condo insurance is two policies that must mesh: the association’s master policy (building, common elements, usually ‘all-in’ or ‘bare walls’ coverage) and your HO-6 (your unit’s interior, improvements, contents, liability, and — critically — loss assessment coverage for special assessments from covered master-policy losses).
The gaps that hurt owners: bare-walls master policies leave unit interiors entirely to HO-6; inadequate loss assessment limits leave owners paying five-figure special assessments out of pocket after hurricanes; deductible stacking — the master policy’s hurricane deductible (a percentage of the building’s insured value, potentially hundreds of thousands) gets assessed across owners. Review your HO-6’s loss assessment limit against your building’s actual exposure — most owners have never done this math.
High-Rise Restoration Logistics
Restoration above the third floor is a different trade. What changes:
Access & scheduling
Freight elevator reservations, loading-dock windows, parking for equipment trucks, and association work-hour rules. Every one needs advance coordination — emergency work still needs building-engineer notification.
Containment in shared air
High-rises share HVAC, corridors, and elevator lobbies. Mold or soot containment must protect common areas and neighboring units — negative pressure, sealed barriers, and corridor protection are standard, not optional.
Water travels down
A 12th-floor leak becomes a 12-through-8 problem. Multi-unit water losses need coordinated assessment across affected units — meter every unit in the water path, not just the one that called.
Association approvals
Most associations require contractor vetting: licenses, insurance certificates naming the association, and work plans. Pre-qualifying your restoration contractor with the association before an emergency saves days.
Hurricane Season: The Condo Checklist
Before June: know your building’s hurricane plan (shutter deployment, garage flooding protocol, elevator shutdown procedures); photograph your unit’s condition; confirm your HO-6’s hurricane deductible and loss assessment limit; know who to call at the association for emergency authorization. After a storm: document damage immediately, mitigate inside your unit (extraction, dehumidification — don’t wait for the association’s roofer), file your HO-6 claim within Florida’s 1-year hurricane claim window, and attend the board meeting where the master-policy claim and special assessment are discussed — that’s where your money gets decided.
For Association Boards & Property Managers
If you manage the building rather than the unit: pre-qualify restoration contractors before hurricane season (vetting during an emergency wastes the critical first 48 hours); keep the master policy, declaration, and emergency contacts in one accessible file; establish the damage-reporting chain for residents now; and understand that common-element water losses need the same moisture-mapping rigor as any other — ‘the hallway dried out’ without meter verification is how mold claims are born. Our property manager restoration path covers commercial-scale response.
Water Intrusion: Florida’s #1 Condo Claim
More condo restoration dollars in Florida go to water than to every other peril combined. The patterns repeat building after building:
Supply-line failures
Aging braided-steel and plastic supply lines burst without warning — often while owners are away. One 3rd-floor burst floods two floors below. Associations increasingly mandate shut-off valves and leak sensors; check your building’s rules.
Water heater ruptures
Tank water heaters have 8–12 year lifespans; Florida’s hard water shortens them. A 50-gallon tank on an upper floor is a five-figure loss waiting for a birthday. Replace proactively.
AC condensate overflows
Clogged condensate lines — Florida’s signature slow leak — saturate ceilings over months before anyone notices. Annual HVAC maintenance with drain-line clearing is the cheapest insurance in the building.
Balcony & window intrusion
Wind-driven rain exploits failed sealant, worn weatherstripping, and deteriorated balcony waterproofing. Post-storm, these are the leaks that ‘nobody saw’ until the drywall bubbled.
Common-line backups
Cast-iron stack deterioration in older buildings causes sewage backups affecting multiple units simultaneously — a multi-unit biohazard loss with shared-plumbing liability questions.
Working With Your Board (Instead of Against It)
Condo restoration goes faster when owners and boards coordinate. Practical steps:
Notify in writing, immediately
Email the property manager and board the day damage is found — photos attached. Verbal reports get forgotten; written reports create the record every claim needs.
Ask for the emergency protocol
Established associations have one: approved emergency contractors, after-hours contacts, elevator procedures. If yours doesn’t, that’s a board-meeting agenda item — before the next storm.
Separate your claim from theirs
Your HO-6 claim and the association’s master-policy claim run in parallel with different adjusters. Don’t wait for the association’s process to start your mitigation — your duty to mitigate is independent.
Attend the money meetings
Special assessments, deductible allocations, and contractor selections are decided at board meetings. Owners who attend shape outcomes; owners who don’t inherit them.
Get everything in the minutes
Verbal board promises about who pays for what evaporate. If it matters, it should be in the meeting minutes — follow up in writing until it is.
Florida Condo & HOA Property Damage Restoration Guide: Common Questions
Who pays for water damage from the unit above mine?
Generally: the upstairs owner’s HO-6 responds for their liability, and your HO-6 covers repairs to your unit. Your association’s declaration defines exact boundaries. Document the source, timeline, and all damage immediately — inter-unit claims depend on it.
What is SB 4-D and how does it affect restoration?
Florida’s post-Surfside law requiring milestone structural inspections for aging condos (30+ years; 25+ near the coast) plus funded reserves. Inspections frequently uncover water intrusion and concrete deterioration that become restoration projects — with statutory deadlines.
What’s the difference between HO-6 and the master policy?
The master policy covers the building and common elements; your HO-6 covers your unit’s interior, contents, liability, and loss assessments. They must mesh — gaps (bare-walls masters, low loss-assessment limits) leave owners exposed.
Does my HO-6 cover special assessments after a hurricane?
Up to your policy’s loss assessment limit — commonly $1,000–$2,000 by default, which is often far below real post-hurricane assessments. Review and raise this limit before storm season.
Can I hire my own contractor for common-element damage?
Generally no — common elements are the association’s responsibility and its master policy’s domain. For damage inside your unit, you hire your contractor but must notify the association and follow its contractor requirements.
How fast must I file a hurricane claim in Florida?
Florida’s hurricane claim filing window is 1 year from the storm. Document and file early — late-filed claims face far more scrutiny.
What should I do about mold in a condo hallway or common area?
Notify the association/property manager in writing immediately — common areas are their responsibility. Document with photos. Don’t attempt remediation in common areas yourself; liability and proper containment require the association’s contractor.
Related Services & Resources
Get Help Now — Emergency Line
Active damage can’t wait. Call (833) 606-6010 or request a callback — we’ll talk through your situation and next steps.